Key Takeaways
- Digital credit enables institutions to borrow, lend, or build credit products on blockchain rails. Whether you want liquidity against your holdings, yield on idle capital, or a new lending line of business, the same underlying infrastructure supports all three.
- Borrowers unlock capital without disposing of assets. You lock digital collateral in a smart contract and receive a loan in minutes, bypassing credit committees and weeks of manual underwriting
- Lenders generate yield from transparent, collateral-backed positions. Idle stablecoins and digital assets generate returns through lending pools, backed by continuous on-chain visibility into every loan.
- Institutions execution requires the right foundation from day one. Custody architecture, compliance integrations, deep liquidity, and automated liquidation mechanics are not secondary decisions; they determine whether your digital credit operation is viable, scalable, and regulatorily sound.
Lending has become one of the largest categories of on-chain activity. As of April 2026, Decentralized Finance (DeFi) lending protocols hold $54 billion in total deposits, according to DefiLlama. That figure reflects more than market momentum; it reflects a fundamental structural shift in how institutional capital moves.
The question in 2026 is no longer whether on-chain credit works. It is how to participate safely, and on what terms. Some institutions want to borrow against digital asset holdings to free up liquidity. Others want to deploy idle capital to capture yield. A growing segment plans to build dedicated digital credit offerings for their own end-clients on blockchain rails. Each path leads to the same foundational question: does the infrastructure behind it meet institutional standards?
Digital credit, at its core, is lending and borrowing executed on blockchain rails, where digital assets serve as collateral and immutable smart contracts enforce loan terms without traditional intermediaries.
What Is Digital Credit and How Does It Work?
Digital credit refers to debt financing executed on blockchain infrastructure, where loans are secured by verifiable digital collateral rather than credit scores, balance-sheet covenants, or income statements.
Here is the simplest way to understand the difference. Traditional bank loans underwrite the borrower. They evaluate your credit history, tax filings, and revenue projections, taking a calculated bet on your future ability to repay.
Digital credit underwrites the asset. Instead of asking “can this borrower be trusted?”, the system asks “is the collateral real, and what is its verifiable market value right now?” As that collateral sits on-chain, anyone can verify its solvency in real time. The facility is secured by verifiable assets that exist today, not by an uncollateralized promise about tomorrow.
That single shift produces downstream effects across settlement speed, accessibility, auditability, and capital efficiency.
How Does Digital Credit Differ From Traditional Credit
The operational contrast between traditional and digital credit is significant:
| Dimension | Traditional Credit | Digital Credit |
| Underwriting basis | Credit score, income history, and financial projections | On-chain collateral value, verifiable in real time |
| Approval timeline | 2–4 weeks of manual underwriting | Minutes via smart contract execution |
| Repayment flexibility | Fixed schedules and early repayment penalties are common | Flexible repayment, governed by protocol parameters |
| Auditability | Internal bank records, limited third-party visibility | Fully transparent on-chain transaction history |
The anchor moment here is the timeline. Weeks of bank underwriting versus minutes of smart contract execution. That compression is not a minor efficiency gain; it changes how institutions can structure liquidity strategy entirely.
Inside the On-Chain Lending Lifecycle
Digital credit protocols execute lending through smart contracts. The process is deterministic: rules are coded in advance, collateral is verified automatically, and liquidation is enforced programmatically.
The Four-Stage Lending Flow
- Borrower posts collateral: Digital assets (such as blue-chip cryptocurrencies, tokenized treasuries, or RWAs) are deposited into a secure smart contract vault.
- Smart contract values the collateral: Real-time decentralized price oracles assess the fair market value of the posted assets.
- Loan is disbursed: The protocol instantly releases funds—typically in stablecoins or liquid digital assets—up to a predetermined Loan-to-Value (LTV) limit.
- Flexible settlement or automated liquidation: The borrower repays on their own schedule. If the market value of the collateral drops to the liquidation threshold, the protocol programmatically auctions or liquidates the assets to protect lender principal.
No credit committee. No administrative delays. The contract executes exactly as written.
Why Over-Collateralization Protects Lenders
Most institutional-grade lending protocols require over-collateralization to insulate against asset volatility. Standard initial collateral ratios sit between 130% and 150% of the loan amount, with automatic liquidation triggers set between 110% and 120%.
For example, a borrower accessing $1 million in credit must lock $1.3 million to $1.5 million in collateral. If market drawdowns compress that buffer toward the $1.1 million to $1.2 million liquidation floor, the smart contract automatically sells the collateral before the lender takes a loss.
These mathematical parameters give institutional risk teams concrete metrics that map directly to internal risk policies.
What Are the Main Types of Digital Credit
The digital credit market spans four distinct models. Each carries a different risk profile and serves different institutional objectives.
1. Over-Collateralized Lending
The borrower locks in collateral that exceeds the loan value. Smart contracts manage valuations and automatically enforce liquidation.
- Use case: Institutions accessing liquidity against digital asset holdings without selling positions.
- Risk level: Low. The structural over-collateralization absorbs price volatility before lender exposure is reached.
2. Under-Collateralized Lending
Loans that exceed collateral value, underwritten by on-chain credit history, reputation scoring, or off-chain legal agreements.
- Use case: Established DeFi participants or institutional counterparties with verifiable track records seeking capital efficiency.
- Risk level: Higher. Default risk is real, and recovery mechanisms are less automated than in over-collateralized structures.
3. Stablecoin Yield
Institutions lend idle stablecoin balances to lending pools, earning yield from borrower interest payments.
- Use case: Treasury management, putting undeployed capital to work without exposure to directional crypto risk.
- Risk level: Moderate. Yield is real, but so is smart contract risk and liquidity risk in pool-based structures.
4. Tokenized Real-World Asset Lending
Physical or financial assets, such as invoices, real estate, commodities, and trade receivables, are tokenized and used as on-chain collateral.
- Use case: Institutions familiar with asset-backed lending who want on-chain settlement efficiency without full crypto collateral exposure.
- Risk level: Variable. Depends on the underlying asset quality, oracle reliability, and legal enforceability of the tokenized claim.
The share of total DeFi value locked by lending protocols rose from 16.6% in January 2024 to over 21% as of mid-2026, per CryptoRank. The category is gaining share within DeFi itself, not simply tracking overall market cycles.
Institutional Cost Structure and Fee Models
Evaluating digital credit requires modeling the total cost of capital beyond headline interest rates.
Costs Borrowers Should Expect
- Interest rates: The primary cost of borrowing. Rates are usually variable and driven by pool utilization: the more capital is borrowed relative to supply, the higher the rate. Institutional borrowers typically see annualized rates ranging from low single digits to mid-teens, depending on the asset and market conditions.
- Origination or borrow fees: Some protocols charge a one-time fee when the loan is opened, often a small percentage of the borrowed amount.
- Liquidation penalties: If your collateral is liquidated, expect a penalty (commonly 5–13% of the liquidated position) paid to liquidators and the protocol. Active collateral management keeps this cost off the books.
Costs Lenders Should Expect
- Protocol fees: Lending protocols often take a cut of the interest earned, known as a reserve factor or protocol spread. This is the gap between what borrowers pay and what lenders receive.
- Performance or management fees: Managed lending strategies and vaults may charge a percentage of yield or assets under management, similar to traditional fund structures.
Costs Builders and Infrastructure Operators Should Expect
- Platform and licensing fees: White-label and API-first providers typically charge setup fees plus recurring subscription or usage-based pricing.
- Custody fees: Qualified custody is usually priced as basis points on assets under custody, sometimes with minimums.
- Compliance tooling: KYT/AML screening is often billed per transaction or per wallet checked.
Network Costs Everyone Shares
- Gas fees: Every on-chain action (posting collateral, borrowing, repaying, liquidating) incurs a transaction fee paid to the network. These fluctuate with congestion. Layer-2 networks and efficient batching can reduce this expense substantially for high-volume operators.
The takeaway: Model your all-in operational stack, not just headline borrowing or lending APYs. For a treasury lending stablecoins, the protocol spread and gas efficiency matter most. For a business launching a branded credit desk, custody and compliance tooling represent the real recurring cost line items.
Key Institutional Risks & How to Mitigate Them
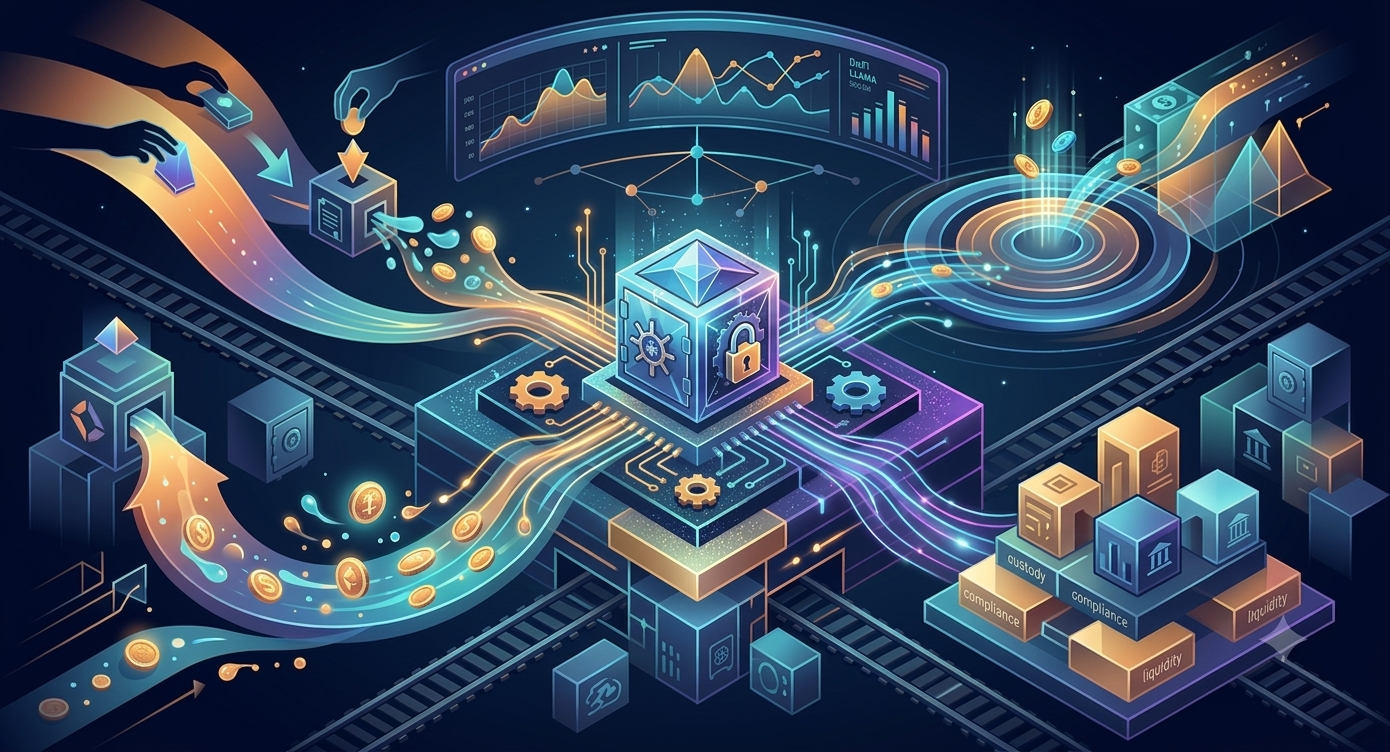
Sound risk management is the non-negotiable prerequisite for enterprise adoption. Three risk categories demand thorough diligence:
1. How Is Collateral Volatility Managed?
- Automated liquidation triggers: Programmed directly into smart contracts and executed without human intervention.
- Dynamic health factors: Real-time margin-call telemetry alerts treasury teams well before liquidation thresholds are breached.
- Collateral whitelisting and caps: Restricting accepted collateral to liquid assets with deep order books limits liquidation slippage.
The critical metric is liquidation execution speed relative to asset volatility: in flash-crash conditions, decentralized oracle latency and network throughput dictate whether lenders stay fully covered.
2. How Is Smart Contract Risk Controlled?
- Independent multi-firm audits: Code reviews by top-tier blockchain security firms are standard for institutional-grade deployments.
- Formal verification: Mathematical proofing of core smart contract logic to confirm execution matches design specifications under all edge cases.
- Bug bounties and coverage pools: Multi-million-dollar developer bounties uncover edge vulnerabilities, supplemented by dedicated smart contract failure insurance.
3. How Does Regulation Apply to Digital Credit?
Regulatory standards are moving rapidly from exploratory statements into formalized regimes:
- European Union: The Markets in Crypto-Assets (MiCA) regulation enforces uniform custody, reserve, and disclosure standards across member states.
- Asia-Pacific: Jurisdictions like Singapore (MAS) and Hong Kong (SFC) provide established licensing frameworks covering digital asset custody, dealing, and credit-adjacent services.
- United States: Regulatory focus centers on qualified custody mandates, lending classification tests, and strict BSA/AML enforcement.
For institutional operators, the practical path to compliance lies in deploying regulated custody alongside automated transaction monitoring. Solutions like ChainUp’s KYT risk control infrastructure provide the screening and auditability institutions require to deploy digital credit within clear regulatory boundaries.
With institutional capital representing approximately 11.5% of total DeFi deposits, adoption is already well underway.The differentiator is operational discipline: deploying capital through platforms that actively control these risk vectors.
How Should Institutions Evaluate Digital Credit Infrastructure
Selecting the right technology provider determines whether digital credit is a scalable competitive advantage or an unmitigated operational risk.
5 Questions to Ask Before Deploying Capital
- Collateral structure: What assets are accepted? How are they valued? What concentration limits apply?
- Liquidation mechanics: At what threshold does liquidation trigger? How fast does execution occur? What happens in illiquid market conditions?
- Custody model: Are assets held in qualified custody? What is the custody provider’s regulatory standing and insurance coverage?
- Insurance coverage: Does the protocol carry smart contract failure insurance? What are the coverage limits and exclusions?
- Regulatory compliance: Is the platform operating under applicable licensing? Does it support KYT/AML requirements for your jurisdiction?
This checklist is designed to be used directly in vendor conversations. If a counterparty cannot answer all five questions clearly, that is itself an answer.
When Should You Build and When Should You Buy
Most institutions should not build digital credit lending infrastructure in-house. The development cost is high, the security requirements are demanding, and the regulatory compliance layer requires ongoing maintenance across multiple jurisdictions.
API-first and white-label infrastructure substantially compresses time-to-market. More importantly, it inherits audited security, meaning institutions benefit from security investments already validated at scale, rather than absorbing that risk themselves.
The build-versus-buy decision simplifies to one criterion: does your institution’s core competency include blockchain infrastructure development? For most fintech operators and financial institutions, the answer is no. The operational and compliance costs of building validate the alternative.
Institutional Digital Credit in Practice: 4 Core Use Cases
Use Case 1: Crypto Treasury Accesses Liquidity Without Selling
A digital asset fund holds substantial long-term Bitcoin and Ethereum positions that it does not want to liquidate for tax and upside reasons. To cover operational expenses, the fund deposits its holdings into a credit protocol at a 150% collateral ratio, borrowing stablecoins within minutes. The treasury repays the facility on its own timeline and reclaims its assets—unlocking non-dilutive liquidity while maintaining long-term market exposure.
Use Case 2: Corporate Treasury Lends Idle Stablecoins for Yield
A cross-border payments company holds sizable stablecoin reserves between settlement cycles. Rather than leaving capital idle, the treasury allocates a portion to audited institutional lending pools. The funds generate predictable interest income without exposing the balance sheet to cryptocurrency price volatility, transforming dormant reserves into an auditable yield engine.
Use Case 3: Regional Bank Launches a Digital Credit Division
A private bank wants to offer crypto-collateralized loans to its high-net-worth clients without building blockchain infrastructure from scratch. By integrating white-label digital credit software, the bank launches a compliant, branded lending product within months—complete with built-in MPC custody, automated liquidation logic, and KYT screening.The bank focuses on client relationships while the underlying platform handles technical execution.
Use Case 4: A Trade Finance Firm Tokenizes Receivables
A trade finance company holds a portfolio of short-term invoices. It tokenizes those receivables and uses them as on-chain collateral to access faster, lower-friction funding. Settlement that once took days now clears on-chain, and the firm bridges its existing asset-backed lending expertise into a more efficient settlement layer, without taking on volatile crypto collateral.
Preparing Your Digital Credit Infrastructure Roadmap
Digital credit transforms lending by verifying assets instead of evaluating reputations. Applied at institutional scale, this model delivers unprecedented settlement speed, total operational transparency, and verifiable risk buffers.
The right implementation model depends on your firm’s specific balance sheet and commercial objectives:
- Over-collateralized borrowing offers the lowest-risk path for treasury liquidity management.
- Stablecoin lending delivers clean, non-directional cash flow.
- Tokenized RWA lending offers the clearest bridge for traditional debt funds transitioning to blockchain efficiency.
ChainUp provides the end-to-end custody, liquidity, and compliance infrastructure necessary to make institutional digital credit viable. From white-label MPC wallet to liquidity technology and automated KYT compliance controls, ChainUp delivers the foundation institutions need to deploy capital on-chain with confidence.
Ready to launch your digital credit operation? Contact the ChainUp team or request a demo today to see our institutional custody, liquidity, and compliance infrastructure in action.
Frequently Asked Questions
What is digital credit in simple terms?
Digital credit is borrowing and lending that happens on a blockchain. Instead of a bank reviewing your credit history, a smart contract evaluates the digital assets you post as collateral and disburses the loan automatically within minutes.
How is digital credit different from a traditional bank loan?
Traditional bank loans are underwritten based on credit scores, income history, and financial projections—a process that typically takes 2–4 weeks. Digital credit is collateral-backed and smart-contract-enforced, settling in minutes. The borrower’s personal history is not a factor; the verifiable value of the collateral is.
What collateral is accepted in digital credit protocols?
Accepted collateral varies by protocol. The most common forms are major cryptocurrencies (such as Bitcoin and Ethereum), stablecoins, and increasingly, tokenized real-world assets (RWAs) such as invoices, real estate, and commodities.
What does over-collateralization mean in digital lending?
Over-collateralization means the borrower must lock up more collateral than the loan value, typically 130–150%. This buffer protects lenders against market drops. If the collateral value falls toward the liquidation threshold (typically 110–120% of the loan value), the smart contract automatically sells the collateral to repay the lender.
Is digital credit regulated?
Yes, but regulatory frameworks vary by jurisdiction. In the EU, MiCA provides a defined compliance structure for digital asset activities. Singapore and Hong Kong maintain licensing regimes for digital asset and DeFi-adjacent services.Institutions should ensure their infrastructure partners operate under applicable licenses and support robust KYT/AML compliance tooling.
What infrastructure does an institution need to participate in digital credit?
At minimum, institutions need four components: qualified custody for digital assets, KYT/AML compliance tooling,access to reliable on-chain liquidity, and an automated liquidation and collateral management framework. Most institutions access these capabilities through established white-label or API infrastructure providers rather than building them in-house.